

Aspire Account Center
3.3

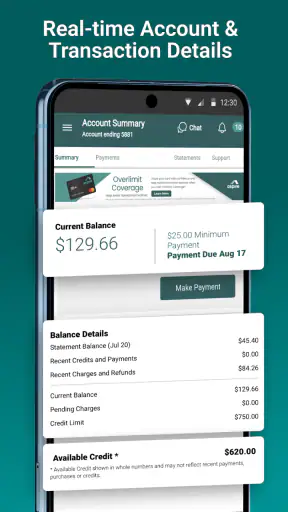
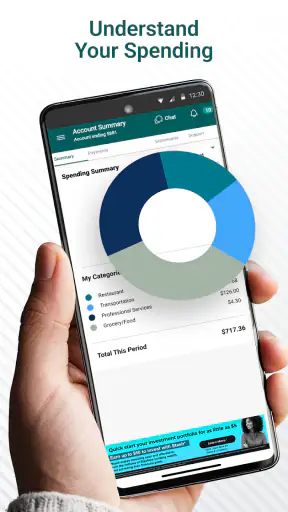
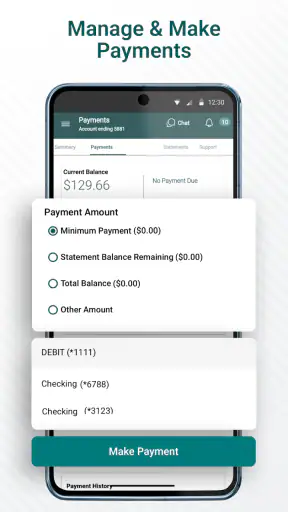
Managing a credit card from a phone sounds simple until a payment is due, a transaction looks unfamiliar, or you need to check your available credit while you are away from a computer. I tested Aspire Account Center with that everyday situation in mind, treating it as a practical finance tool rather than as a full replacement for every money app on my phone. Its purpose is focused: it brings Aspire credit-card account management into one mobile place.
That narrow focus is both its main strength and its first limitation. I would not choose it to build a complete household budget, track several unrelated banks, or replace a dedicated expense app. I would choose it when my immediate task involves an Aspire card and I want to handle that task without opening a browser or searching through old messages. The experience is most useful when the starting point is clear: I need to inspect the account, understand what needs attention, and complete the next step with as little wandering as possible.
From a pending card task to a completed account check
Starting with the right expectation
Aspire Account Center is a free finance app from Atlanticus Services, available for everyone and designed for use on Android devices running at least Android 6.0. It first appeared on June 25, 2019, and the current version is 4.22.47-6102. Those details matter less than the practical expectation they set: this is an account-center companion for Aspire credit cards, not a general-purpose financial dashboard.
Before opening it, I find it helpful to decide what I am actually trying to do. If I only want to check a balance or review recent card activity, a focused account app makes sense. If I am trying to compare spending across several cards, categorize groceries against transport, or see savings and checking accounts together, I would start with a broader personal-finance tool instead. The app works best when the card itself is the center of the task.
The app has passed the point where it feels like an unknown experiment. It has more than 500 thousand installs, with an average rating of 3.3 from about 2.1 thousand ratings. I read that as a mixed but understandable signal: enough people use it for the core purpose, while the experience may not feel equally smooth for every account holder or every phone. I would install it for a specific need, but I would still keep another way to reach the account available until I had completed the first important task successfully.
Step one: opening the account center
My first step in a realistic workflow is to open the app when I have a concrete reason, such as checking whether a recent purchase has appeared or confirming what is owed before making a payment. That approach is better than casually browsing because finance apps are most valuable when they answer a question quickly. I want the opening screen to lead me toward the account rather than encourage me to explore unrelated features.
For a first-time user, the important handoff happens between the app and the account itself. The app is only useful once it can connect me with my Aspire card information. I would have my account details ready, use the official sign-in route presented by the app, and avoid entering financial credentials into any page reached through an unexpected message. That is not a special feature claim; it is simply a sensible habit whenever a mobile tool handles card access.
One useful tip is to install the app before an urgent deadline instead of waiting until the moment a payment is due. That gives me time to sign in, confirm that the account appears correctly, and learn where the information I need is located. If something goes wrong, I can switch to the usual account website or another official support route without turning a routine payment into a last-minute problem.
Step two: turning a vague concern into a specific check
Once I reach the account area, I would work from the question that brought me there. For a balance check, I want the current account figures and enough context to understand what they mean. For a transaction check, I want to distinguish a recent purchase from an older charge or a pending item. For a payment-related task, I want to verify the destination and amount before confirming anything.
This is where a specialized app can be more comfortable than a general banking app. A general finance application may combine accounts beautifully, but it can also hide card-specific actions behind several layers. Aspire Account Center keeps the workflow tied to the Aspire card relationship. That reduces mental switching when I am not trying to manage my entire financial life and only need to answer, “What is happening with this card?”
I would not treat a displayed balance as a complete explanation of my finances. A card balance can change as transactions move through different stages, and a payment can affect what I see without solving every question about a purchase. My practical routine would be to look at the amount, review the related activity, and then check the date and purpose before acting. The app is a useful control panel, but I still need to interpret the information rather than tap through automatically.
Step three: reviewing activity before taking action
Reviewing activity is an underrated part of card management. When I notice a charge I do not immediately recognize, I would first compare its timing and amount with receipts, subscriptions, delivery orders, or purchases made by someone authorized to use the card. That short pause can prevent an unnecessary dispute over a legitimate transaction. It also helps me spot recurring charges that I may have forgotten about.
This workflow is especially useful after a busy day. Imagine I am leaving a supermarket and remember that I made a larger purchase earlier in the week. Instead of waiting until I am home at a computer, I can open the account center, look for the recent activity, and compare the entry with my receipt. The outcome is not just convenience; it is a faster decision about whether the charge is familiar, still pending, or worth investigating through the appropriate support channel.
A second non-obvious use is preparing for a conversation with support. If I have already checked the account and noted the approximate transaction details, I can explain the problem more clearly instead of beginning with a vague statement that “something looks wrong.” The app does not remove the need for support, but it can improve the handoff by helping me arrive with a more precise question.
Step four: completing the payment or account task carefully
When the goal is a payment, I prefer a deliberate sequence: confirm the account, check the amount, review the timing, and only then submit. The convenience of a phone can work against me here because a quick tap feels harmless even when the result affects my credit-card account. I would also save enough time to verify that the action has been acknowledged before closing the app.
This is one of the places where I would judge the app by clarity rather than by visual polish. Financial screens should make it obvious which figure I am viewing and which action I am about to take. If I ever feel uncertain about whether a payment was actually submitted, I would not repeat it immediately. I would first refresh the account or check the available confirmation information, then use the official account or support route if the status remains unclear.
That caution is also why I would not rely on a single mobile session for an important deadline. The app can make the task easier, but a failed connection, expired session, or unclear status can create avoidable stress. My preferred workflow is to complete the task early enough that I have time to verify the outcome and use an alternative channel if necessary.
The handoffs that shape the experience
The app is only one link in the chain. The first handoff is from my real-world concern to the information shown in the account. The second is from the account information to an action, such as reviewing a charge or making a payment. The third is from the app to support when the issue cannot be resolved by checking the screen alone. Thinking about those handoffs helps explain why a focused account center can feel excellent for one task and insufficient for another.
For example, the app may help me identify a transaction, but identifying it is not the same as resolving a disputed charge. Likewise, seeing account information is not the same as understanding my complete monthly budget. I appreciate the app most when I respect that boundary. It gives me a direct place to begin, while the next step may involve a receipt, another account, or a conversation with the card provider.
Another handoff occurs when I move between phone and desktop. I might start by checking the account on mobile, then use a browser if I need a larger screen for a more involved review. That is not a failure of the app; it is a realistic division of labor. A phone is ideal for a quick check in a queue or before a purchase, while a desktop can be more comfortable when I need to compare several records carefully.
What the completed workflow achieves
The best result is a small but meaningful reduction in uncertainty. I can check the Aspire card when I need to, understand whether a recent item is present, and decide whether the next move is routine account management or a support request. That is a more useful outcome than simply saying the app is “convenient,” because it describes the moment when the convenience matters.
I also like the possibility of building a repeatable habit around it. Once a week, I could review recent card activity, note anything unfamiliar, and confirm that my upcoming payment plan still makes sense. The value comes from the routine, not from leaving the app open all day. A focused tool is often better used briefly and intentionally than treated as a permanent financial command center.
For someone who holds an Aspire card and wants mobile access to that account, the app is a sensible first option. Its free price removes the need to pay for basic access, and its Everyone content rating makes it approachable for ordinary household use. I would still encourage a new user to complete a low-pressure account check first, learn the navigation, and only then depend on it for time-sensitive tasks.
Where the flow breaks down
The main weakness is the narrow scope. If I want one screen containing my Aspire card, another issuer’s card, a bank account, investments, and categorized spending, this app is not the right tool. A broader money-management app will usually be better for that overview, even if it is less direct for Aspire-specific account work. Using this app as a full budget planner would leave too much of the picture outside the workflow.
The mixed rating also makes me cautious about assuming a flawless experience on every device or account. I would not invent a specific technical problem and call it universal, but I would take the rating as a reason to keep expectations practical. If sign-in, loading, or account display becomes unreliable, I would update the app, retry on a stable connection, and then move to the official web or support alternative rather than repeatedly forcing the same failed step.
There is also a human limitation: quick access can encourage quick decisions. A mobile screen is convenient for checking a charge, but it may not provide the same comfort as a larger display when I am reconciling many purchases. I would skip the app for a long financial review and use a more spacious method instead. The best choice depends on whether I need speed or a complete audit.
People who dislike managing financial accounts on a phone may also prefer the usual browser route. The app does not automatically make card administration effortless; I still need to remember my credentials, interpret account figures, and follow up when an issue requires assistance. Its contribution is removing some friction from access, not removing responsibility from the process.
Who should install it, and who should look elsewhere
I would recommend Aspire Account Center to an Aspire cardholder who regularly checks account activity, wants a mobile-first way to stay informed, or needs a convenient starting point before contacting support. It is particularly useful for short sessions: checking a recent purchase after leaving a store, reviewing the account before a payment, or confirming that a card-related question is worth escalating.
I would suggest looking elsewhere if the main goal is household budgeting, multi-bank aggregation, investment tracking, or detailed spending analysis. In those cases, a dedicated personal-finance app or the separate apps for each financial institution may provide a clearer overall picture. I would also avoid making it my only access method until I had tested the workflow on my own device and confirmed that the account information and actions behave as expected.
After using it as a complete input-to-outcome workflow, my view is measured but positive. The app is not trying to be every financial tool at once, and that focus is valuable when the task begins and ends with an Aspire credit card. It helps me move from concern, to account review, to a sensible next action, while leaving room for browser access or support when the issue becomes more complicated.
My recommendation is to treat Aspire Account Center as a focused card-management companion, not as a complete money-management system. For the right user, that distinction makes it easier to decide whether the app belongs on the phone: install it for direct Aspire account access, test the important workflow before a deadline, and use a broader alternative when the financial question extends beyond that single card.
3.3
967.00 Reviews
Pros
- Centralizes account management in one convenient mobile app.
- Makes it easy to review balances
- transactions
- and account activity.
- Provides quick access to Aspire support and account assistance.
- Reduces the need to manage account details through multiple channels.
- Useful for checking financial information while traveling or away from a computer.
Cons
- Some features may depend on the type of Aspire account you hold.
- Requires a stable internet connection for most account functions.
- Security verification can make sign-in slower on some devices.
- The interface may feel limited compared with a full online banking portal.
- App availability and features may vary by region or account eligibility.


